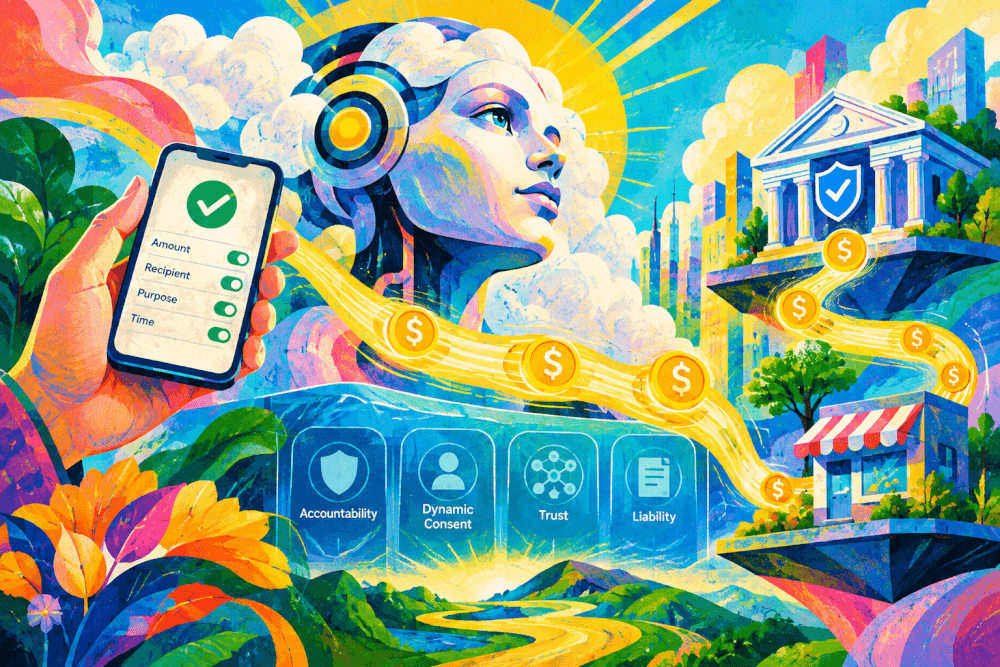
The rise of AI agents that can initiate payments creates accountability questions that go beyond traditional cybersecurity. When software, not a person, decides to move money, payment providers, banks and merchants must address fraud risk, liability allocation and customer trust at the protocol level.
The New Frontier: AI Autonomy and Consent
Traditional consent models rely on one-time approvals or broad terms of service. Those approaches fail when agents act continuously or adaptively on behalf of users. Dynamic, granular consent means permissioning that evolves with agent behavior: scoped rights, time bounds, transaction thresholds and immediate revocation.
Key elements of dynamic consent:
- Scoped permissions tied to explicit use cases and transaction types.
- Real-time consent tokens that expire or require reauthorization for high-risk actions.
- Transparent UI and machine-readable policies so users and systems can verify agent scope.
- Audit-ready logs linking consent events to every payment decision.
Industry voices including xpate argue that consent must be both human interpretable and enforceable at the protocol layer if providers want to limit exposure.
Crafting a Framework for Responsible AI Payments
Payment providers should treat AI payments as a new operational domain with specific governance, controls and contract terms. Practical steps:
- Set explicit agent limits: per-transaction caps, daily aggregates and whitelisted counterparties.
- Implement decision tracing: immutable provenance, tamper-evident logs and explainability metadata attached to each payment.
- Define liability rules in contracts and API terms: delineate responsibilities between platform, integrator and end user, and require incident reporting timelines.
- Deploy continuous fraud detection tuned for agent patterns and automated challenge flows for suspicious actions.
- Require indemnity or insurance where appropriate and run periodic red team reviews of agent behaviors.
Adopting these measures early reduces regulatory friction and builds customer confidence. Start with limited pilots, clear governance, legal review and a communications plan that makes agent activity visible to users and regulators.
Proactive accountability is not only a compliance step. It is a strategic move that preserves trust as payments become increasingly autonomous.